Insurance Cover Can Double to 30% in 5 Years, Says IRDAI Chairman; Account Aggregators Seen as Key Partner
IRDAI sees account aggregators as key partners in improving insurance penetration and helping India achieve its target of 30% insurance cover over the next five years.
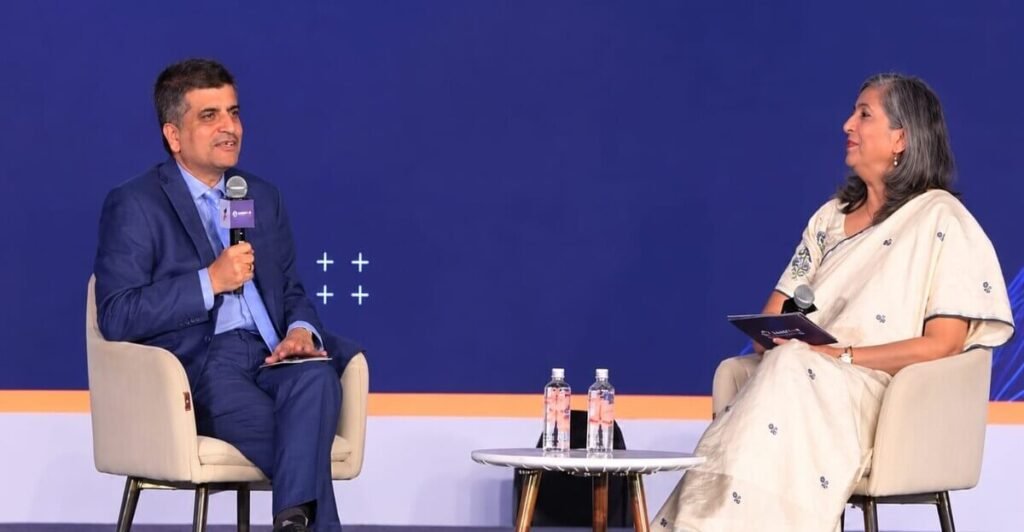
IRDAI Chairman Ajay Seth says insurance cover could double to 30% in five years, with account aggregators expected to play a key role in expanding insurance access.
NEW DELHI – IRDAI Chairman Ajay Seth has said India can double effective insurance cover from about 15% to 30% in five years, and that the Account Aggregator (AA) framework can be a partner in getting there. All life insurers and about 90% of general insurers have joined the framework, but its usage in insurance remains below 1%, the interviewer noted at the event involving Sahamati, the self-regulatory organisation for the AA ecosystem.
IRDAI: Regulator’s estimate: at most 15% have effective cover
Seth said the industry currently tracks the number of policies sold and the premium collected each year, but does not track the number of lives covered or the total sum insured. Based on his best estimate, he said, at most 15% of the country’s population and economic enterprises have an effective cover. Doubling that to at least 30% within five years is possible, he said, calling it his view.
Speaking in a live interview, Seth said he was “a firm believer” that usage of the AA framework would grow sharply, as it has in other sectors where digital public infrastructure (DPI) has succeeded in the country. He cited Sahamati’s recognition as a self-regulatory organisation a few months ago and the recently discussed cost structure as building blocks now falling into place.
Also Read: Crop Insurance Claims May Rise in Maharashtra, Karnataka, AP as Drought Spreads
IRDAI: Digital the way forward, intermediaries to stay
Asked whether he sees the AA ecosystem as a partner in expanding cover, Seth replied, “Certainly.” He said distributors and intermediaries will always be important as advisers in insurance, since a large part of the population and of economic enterprises will need them. At the same time, he said, digital is the way to move forward, with some customers wanting to buy insurance on their own and others preferring assisted services.
Seth said insurance has to expand beyond the top 10% income decile into lower income groups, and into smaller cities. He noted that even in a city with a population of half a million, it is difficult to serve customers through a model that depends on human intermediaries alone. AA infrastructure, he said, can make insurance services far more affordable than they have been.
On how to raise usage of the framework in insurance, Seth said efforts so far have been on the supply side, with pilots to check whether an insurer and an account aggregator can connect. The sector now needs to generate enough demand, he said, by considering what would make the framework worthwhile for micro-enterprises, small businesses and individuals. He pointed to UPI, which took off in 2016 once such a pull factor emerged. IRDAI, as a development authority as well as a regulator, and Sahamati, as a self-regulatory organisation, will need to work together on this, he said.
IRDAI: Where the regulator sees Account Aggregators fitting in
Seth said financial information shared through the AA framework is relevant to insurance mainly in underwriting. When a person seeks high pure-protection cover, he said, the insurer needs to examine whether the cover is warranted, which makes the individual’s financial information important. For cover of ₹50 lakh or ₹1 crore, annual income is a key input, he said, and he referred to the commonly advocated guideline of cover worth about 10 times annual income. “At the moment, we have not been using it,” Seth said. The only use case attempted so far, he added, is lending against the surrender value of a policy.
While preparing a concept paper on the Public Insurance Registry, IRDAI identified at least seven use cases where the framework could be expanded, Seth said. Each requires further work, and each could become a pull factor, he said. One is premium financing for policyholders who are at risk of lapsing.
He said a significant number of people surrender their policies because they need money, and that non-salaried policyholders may see their income dry up with two to four instalments still pending. Financing those last instalments could let them receive the full value of the policy after a couple of years, with little risk to the lender because of the policy’s embedded value. He said a grey market has developed in which people are asked to assign their policies, which is not the right course under the Insurance Act, and that this could be formalised through a proper premium financing channel.
On health insurance, Seth said paying a full year’s premium can be difficult for a family earning ₹50,000 a month. Insurers do not accept monthly payment on health policies, so the premium has to be financed in one go. A 12-month instalment arrangement could work, he said, but only if the economics suit the customer. He noted that lenders sometimes charge up to 20% interest, a rate at which no one would borrow to buy insurance. “It has to be 10-12%, then it will work,” he said, adding that financial information gives lenders confidence that such a loan is as good as a secured one.
Other uses he described included helping lenders, including small ones, collect quotes from insurers to cover their own portfolios, which is currently done informally. A lender could also use an enterprise’s insurance history as an indicator of whether it is a responsible borrower, he said, citing a business that has paid property insurance premiums for 10 years. Seth described surety bonds, issued in place of bank guarantees, as a large emerging area. Issuing them requires a contractor’s credit history or capital, its contract performance record and its insurance history, he said, and there is currently no rail to pick up that information.
The last use case Seth mentioned was the Reserve Bank of India’s Unified Lending Interface, which deals in low-value, high-volume loans. Insurance linked to such loans would have to be offered within the electronic flow itself, he said. He flagged an economic challenge: on a ₹30,000 loan the premium may be about ₹100, and if ₹6 of that went towards accessing financial information, the model might not work. Micro-finance insurance, he said, requires development work from the end user’s point of view.
Seth said the Public Insurance Registry and Bima Sugam are meant to build on existing DPI and to complement it, not replace it. Bima Sugam, conceptualised about two years ago, is a customer-facing platform for buying insurance directly with no intermediary, and it will need financial information and a consent architecture that AA infrastructure already provides, he said.
The Public Insurance Registry is a business-facing infrastructure for which eight use cases have been identified for financial institutions, six of which need AA participation, he said. With about 60 insurers collecting, storing and exchanging data in different ways, a common rail and protocol is needed first so that the AA network can connect to it and move data between providers and users.
Asked whether the AA-based fraud monitoring that banks use on field staff accounts could be applied to insurance distributors and agents, Seth said IRDAI has not gone into this area. He contrasted banks, which handle public money at very large scale, with insurance, and said getting into the bank accounts of insurance participants “may be a stretch” at this stage. The regulator favours a less intrusive approach centred on good market conduct, which he said could be far more effective.