India’s Insurers Are Spending Faster Than They Are Selling, McKinsey Finds
Insurers are spending faster than they are selling, according to McKinsey, as rising costs put pressure on growth and profitability across India’s insurance sector.
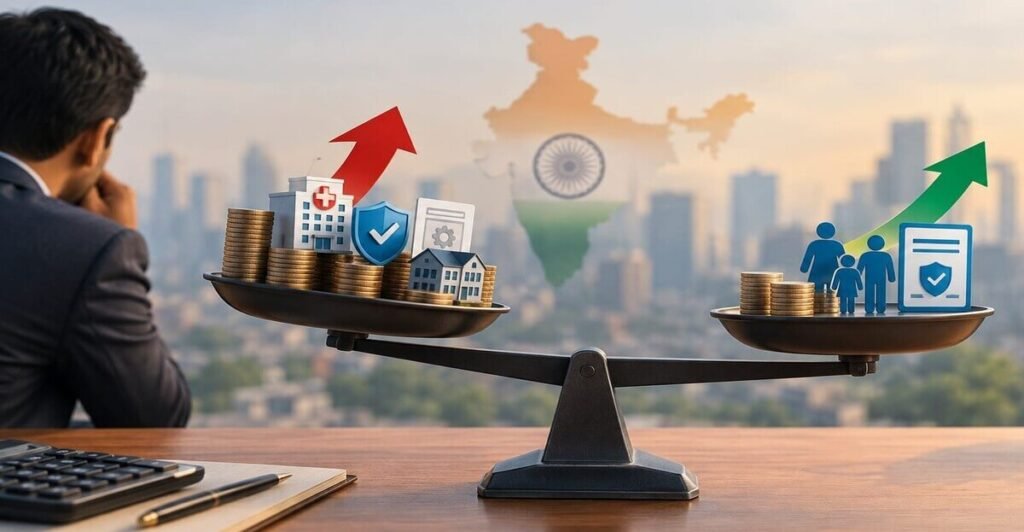
Insurers are increasing their spending faster than premium growth, raising concerns over rising costs and efficiency. McKinsey’s latest findings highlight the widening gap between insurer expenses and sales.
New Delhi, Insurers: India has opened bank accounts for nearly nine in ten adults, built a national digital identity system and put financial services on the phone. Yet insurance still accounts for just 3.7 per cent of the country’s GDP, a little over half the global average of 7.3 per cent, according to a new McKinsey report. The report adds that the cost of running India’s life insurers has been climbing faster than the premiums they bring in.
The findings arrive as the Insurance Regulatory and Development Authority of India (IRDAI) examines the economics of how insurance is sold, including commissions and distribution costs.
Insurers: A Gap Concentrated in Non-Life Insurance
McKinsey put India’s overall insurance penetration at 3.7 per cent of GDP in FY25, against a worldwide average of 7.3 per cent. Most of the shortfall lies in non-life insurance, which covers areas such as health, motor and property. Non-life penetration was just 1 per cent of GDP, while life insurance stood at 2.7 per cent.
Insurers: Expenses Growing Faster Than Premiums
The report analysed private life insurers over FY22 to FY25. Their new business premium grew at a compound annual rate of about 14 per cent, while total operating expenses rose at around 20 per cent a year. McKinsey said productivity at the leading life insurers stayed broadly flat over the period, while sales and distribution costs faced mounting pressure.
The report also found that bigger premium numbers have not meant more customers. Across the life insurance industry, individual new business premium grew at about 10 per cent a year between FY22 and FY25, but the number of individual policies fell by roughly 2 per cent a year. McKinsey said this indicates that premium growth is coming mainly from larger policy sizes rather than from selling more policies.
Insurers: Access Has Improved, but Insurance Has Lagged
The report contrasts insurance with the rest of India’s financial system. Adult bank account ownership rose from 53 per cent in 2014 to 89 per cent in 2024, and participation in demat accounts and other investment products has also expanded sharply. Insurance uptake has not moved at the same pace.
McKinsey argued that the obstacles are no longer access to the formal financial system, identity documents or digital channels, all of which it said now exist. In its words, the constraints are “product relevance, distribution alignment, and trust at the moment of risk.”
Insurers: Regulatory Context
IRDAI is weighing ways to lower distribution costs and tighten safeguards against mis-selling, while making sure insurers can still reach underserved markets. The regulator’s review is aimed at improving affordability, transparency and sales practices.
Looking ahead, McKinsey said the next phase of growth will depend less on basic access and more on product relevance, affordability, distribution effectiveness and customer trust. It also pointed to technology and artificial intelligence as tools for improving productivity, underwriting, claims handling and customer servicing.