PB Fintech Under Fire: HSBC, Motilal Oswal, BofA, Jefferies Slash Targets Up To 45%
PB Fintech faces a fresh wave of target cuts from HSBC, Motilal Oswal, Bank of America and Jefferies.
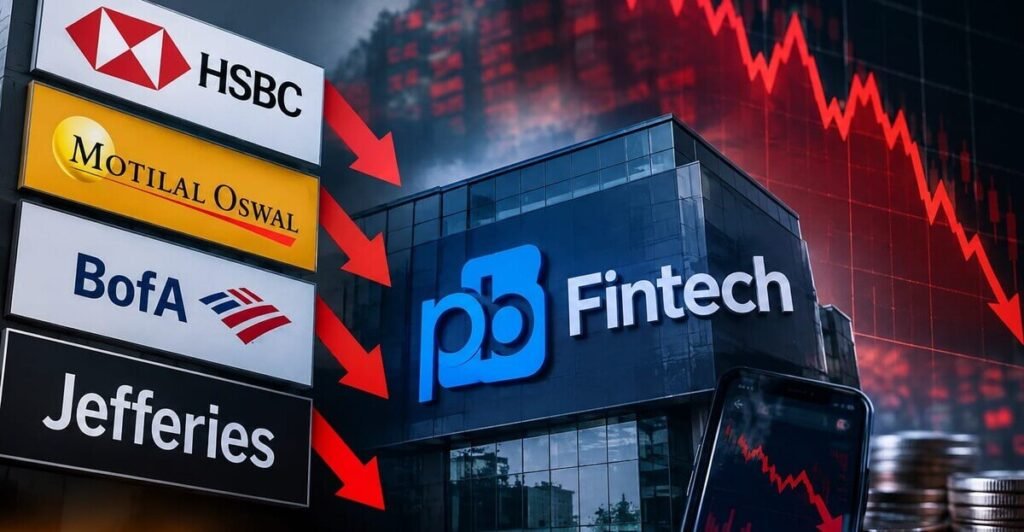
PB Fintech has come under pressure as major brokerages cut their price targets by up to 45%, citing concerns over the company’s outlook.
PB Fintech: Five years after PB Fintech listed on the stock exchanges at ₹1,150 a share, that number is back at the centre of the conversation around the stock — this time as the new price target set by two of the five brokerages that revised their estimates on the company this week.
HSBC, Motilal Oswal, Bank of America, Jefferies and Morgan Stanley all cut their target prices on PB Fintech, with HSBC downgrading the stock to “Hold” from “Buy,” after the Insurance Regulatory and Development Authority of India (IRDAI) floated draft distribution reforms that could cap commissions paid to platforms like Policybazaar. The five brokerages cut their target prices by between 25% and 45%, with HSBC and Motilal Oswal both settling on ₹1,150 as their new target, while BofA and Jefferies took a comparatively less severe view.
HSBC lowered its target price on PB Fintech to ₹1,150 from ₹2,100, a cut of roughly 45%, and shifted its rating to Hold. The brokerage said the proposed reforms, which include commission caps for insurance companies, could have a material impact on the company. HSBC cut its earnings-per-share estimates for PB Fintech by 56% for FY28 and 17% for FY29, noting that the hit from lower take rates would be partly offset by slightly higher growth assumptions and cost savings. The brokerage said further regulatory clarity would be the key catalyst for the stock going forward.
PB Fintech shares were trading around ₹1,207 on Friday, recovering some ground after a sharp fall in the previous session, with the stock rising as much as 4.5% intrada
Also Read: PB Fintech Analyst Call: Insurance Licence on Table, No Mass Layoffs, Hiring To Slow
PB Fintech: Motilal Oswal Flags Up To 46% Hit To Earnings In Worst-Case Scenario
Motilal Oswal Financial Services (MOFSL) also cut its target price on PB Fintech to ₹1,150 while retaining a Neutral rating. The brokerage said the company held a call to discuss the implications of the draft rules and indicated that, if implemented as proposed, the changes could result in a roughly 30% hit to FY28 core online insurance revenue.
According to Motilal Oswal, a 30% cut to core online insurance revenue estimates, without any offsetting adjustments to expenses or additional revenue streams flagged by the company, would translate into a 46% decline in earnings estimates — a scenario in which the stock would trade at 73 times earnings. If PB Fintech is able to cut employee and advertising costs by 20% relative to current assumptions, the brokerage estimated the earnings cut would be limited to around 30%, with the stock trading at 57 times earnings instead. Motilal Oswal said it expects the stock to continue underperforming until the final regulations are announced.
PB Fintech – BofA, Jefferies and Morgan Stanley Offer A More Measured View
Other brokerages were less severe in their reassessment. Bank of America (BofA) retained its Neutral rating on PB Fintech but cut its target price to ₹1,410 from ₹1,970, a reduction of about 28%. BofA said the impact on the company’s life and term insurance business appears manageable and that it sees room for PolicyBazaar to gain market share across categories, adding that risks around asymmetric commission cuts — a concern flagged earlier by investors — are now largely behind the company.
Jefferies maintained its Buy rating but trimmed its target price to ₹1,540 from ₹2,050, a cut of roughly 25%. The brokerage said it expects a larger impact on the net present value of the non-life business relative to life insurance, and that the company’s near-term focus is likely to shift toward cost optimisation. Jefferies estimated that a 10% cut in new-business commission rates could translate into a 10–12% decline in earnings, while noting that the proposals remain part of a consultation paper that could still change after stakeholder feedback.
Morgan Stanley said the net present value of the health insurance business could fall by 60–70% under the proposed framework, while the life insurance business is expected to remain broadly stable. The brokerage said PB Fintech is evaluating options including insurance manufacturing, reinsurance broking and new products, and is seeking a regulatory framework for managing general agents (MGAs) that rewards quality distributors. Morgan Stanley added that lower premiums could support demand growth, that the company has flagged no immediate layoffs, and that it sees cost headroom along with plans to narrow losses at Paisabazaar and its UAE operations, while flagging a risk to the topline of PB Partners, its point-of-sale agent network.
PB Fintech: What Triggered The Reassessment
The brokerage downgrades follow IRDAI’s draft proposals on insurance distribution reforms, which include commission caps for insurers and are currently out for consultation. Several brokerages, including Jefferies and Motilal Oswal, noted that the proposals could still be revised after stakeholder feedback is incorporated.
PB Fintech listed on the stock exchanges in 2021 at ₹1,150 per share against an IPO price of ₹980.