Bharat Griha Raksha: Why You Need This Home Insurance Policy
Bharat Griha Raksha is a home insurance policy designed to protect your house and belongings against covered risks.
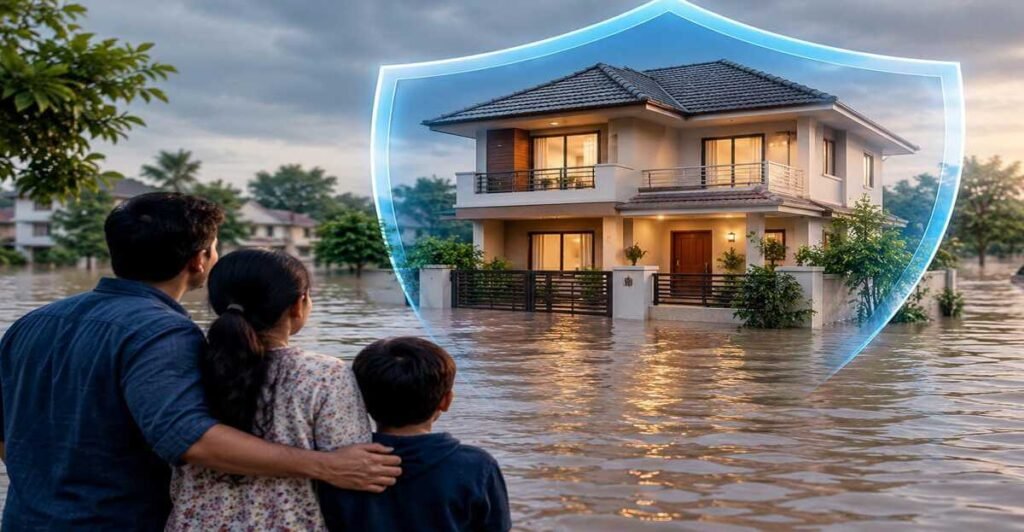
Bharat Griha Raksha offers protection for your home against a range of risks, helping homeowners manage unexpected losses.
Bharat Griha Raksha, the standard home insurance product prescribed by the Insurance Regulatory and Development Authority of India (IRDAI), covers residential buildings and household contents against fire, natural calamities, theft and other listed perils. General insurers have been required to offer the policy since 1 April 2021.
The regulator announced the product on 4 January 2021. It replaces the Standard Fire and Special Perils policy for dwellings, which followed the All India Fire Tariff, 2001. Insurers must offer it on both new business and renewals.
Bharat Griha Raksha: What the Policy Covers
Under the policy, insurers cover loss or damage from fire, storm, cyclone, tempest, hurricane, tornado, tsunami, flood, inundation, earthquake, subsidence, landslide and rockslide. The list also includes forest and bush fires, impact damage, riot, strike, malicious damage, acts of terrorism, bursting or overflowing of water tanks, apparatus and pipes, leakage from sprinkler systems, and theft. Losses are covered if they occur within seven days of an insured event.
The policy applies to independent houses, villas and flats in housing societies, whether owned or rented.
Also Read: BRICS Summit: Why Trump May Be Taking a Close Look at Iran’s Insurance Pitch in India
Household contents are covered automatically, without a declaration of details, for 20 per cent of the building’s sum insured, capped at Rs 10 lakh. In an example cited by Chola MS General Insurance Managing Director Suryanarayanan V, a home insured for Rs 15 lakh under the affordable housing segment would carry Rs 3 lakh of automatic contents cover. The cover applies only if the customer opts for it. Higher cover requires an additional premium and a declaration of the value of specific items.
Two optional covers are available, one for valuables such as jewellery and curios on an agreed-value basis, and one for personal accident to the insured or spouse. Bajaj General Insurance lists the personal accident benefit at Rs 5 lakh. Built-in benefits include removal of debris, rent for alternative accommodation, and architect and surveyor fees.
Bharat Griha Raksha: Exclusions and Under-Insurance Rules
Insurers list natural wear and tear, gradual deterioration, pollution, war, radioactive emission and wilful acts or omissions among the exclusions. Tata AIG General Insurance’s Srabasti Dhali said claims may be denied if a property is used for non-residential purposes.
The policy does not offer a full waiver of under-insurance. Where the declared sum insured is lower than the actual value, the payout is limited to the declared amount. Policybazaar illustrates this with contents insured at Rs 50,000 but valued at Rs 1 lakh, which would be paid at Rs 50,000. Dhali said under-insuring can complicate claims, while over-insuring can lead to unnecessary expense.
Premiums vary with the sum assured, age and location of the property, construction quality and safety features, according to Dhali. Annual policies are available, and insurers also offer long-term policies of two, three and up to 10 years.
Bharat Griha Raksha: Claims Process
Under the claims process described for National Insurance Company’s version of the policy, the insured must notify the insurer immediately after a loss. The notice should include the policy number, details of the event and any police report. Photographs of the damage are to be submitted where possible, and the claim form is due within 30 days of the loss first being noticed. Losses from theft, fire or other criminal or emergency events are to be reported to the police or fire authorities. The insured is also required to take reasonable steps to prevent further damage.
Suryanarayanan V said home insurance carries particular relevance during the monsoon, when the risk of floods, inundation and cyclones is high. Timelines and procedures may differ across insurers.
Before publishing, add your byline and confirm figures against the specific insurer’s IRDAI-approved policy wording. I found no fresh news development in my search, so the piece is written as a news feature on the policy. If you have a current hook, such as a circular or a calamity, it should replace the opening paragraph.