IRDAI moves to ban ‘dark patterns’: you may soon see prices without giving your phone number
IRDAI proposed measures aim to make insurance buying more transparent and consumer-friendly. Customers may soon be able to check policy prices without first giving their phone number.
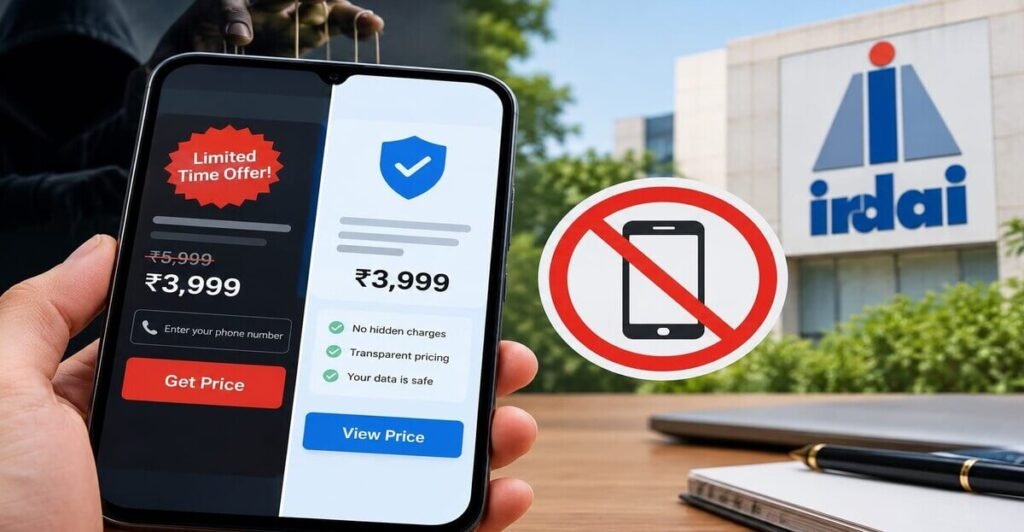
IRDAI is moving to curb dark patterns in insurance, including practices that push consumers to share phone numbers before viewing prices.
IRDAI: If you have tried to check the price of a health or term plan online, you know the routine. Before you see a single premium, the website asks for your name, mobile number and email. Within minutes the calls start.
The Insurance Regulatory and Development Authority of India (IRDAI) now wants to end that. In its public consultation paper Recalibrating Economics of Insurance Distribution, released in September 2026, the regulator proposes to prohibit “dark patterns” under insurance regulations. It says plainly that information access “should not be used as a lead generation opportunity.”
IRDAI: What IRDAI means by a dark pattern
The paper defines dark patterns as deceptive interface or user-experience designs that mislead or trick people into doing something they did not intend to do. It says such designs undermine consumers’ autonomy and choice, and can amount to misleading advertising, an unfair trade practice or a breach of consumer rights. The definition matches the one used by the Central Consumer Protection Authority (CCPA), which issued dark-pattern guidelines under the Consumer Protection Act, 2019.
The regulator names one practice directly: making product features and prices visible only after the buyer shares personal details. It describes this as a dark pattern “often seen in the websites of most insurers and distributors.” It adds that the practice already runs against the CCPA’s guidelines.
Under the proposal, the following would have to be freely available without asking for a name, phone number, email or any other identification:
- the product information sheet,
- the FAQ note,
- the detailed brochure,
- premium rates,
- product and service-quality performance data.
Also Read: PB Fintech Under Fire: HSBC, Motilal Oswal, BofA, Jefferies Slash Targets Up To 45%
IRDAI – The shift: from being “sold” to buying
The dark-patterns clause is short, but it supports a larger idea in the paper. IRDAI notes that the industry has long worked on the principle that “insurance is sold.” It wants to nudge the market towards “insurance is also purchased,” meaning customers compare products on price and quality rather than being steered by whoever pays the salesperson most.
The regulator’s own numbers show why this matters. Life policies bought online survive to the 61st month in 71% of cases. Across the industry, the figure is only 48%. The paper reads this as evidence that informed buyers choose better-suited products and keep them.
IRDAI: One page, plain language
The Life Insurance Council and the General Insurance Council would be asked to create standard formats for a one-page information sheet and an FAQ note for every class of insurance product. Insurers would have to explain key features in simple language. A disclaimer would state that the full policy wording still governs in any legal dispute.
The paper also says product features are “not often disclosed in a cogent form” today, and that making product, pricing and quality information available would become a regulatory requirement rather than a courtesy.
IRDAI – Claim settlement ratios that mean something
Buyers often choose an insurer by its “claim settlement ratio.” IRDAI points out that health insurers usually count claims decided, not money paid. Claims that were partly paid, repudiated or rejected all count as “decided.” A company can therefore report an impressive ratio while paying out far less than policyholders claimed.
The regulator says the ratio that matters to policyholders is the amount paid as a share of the amount claimed. It plans to issue standard definitions for performance and quality measures. The gap is large: Part 2 of the paper shows FY25 health claim settlement ratios, measured by amount, from 29% to 94% across general insurers, with an industry average of 75%.
The paper also flags complaints being logged as “service requests,” which keeps them out of grievance statistics. Clearer rules on what counts as a grievance are planned.
IRDAI: Commissions in plain sight
Insurers would have to publish their board-approved commission policy, including rewards and related payments, on their websites. It must be reachable within one click of the landing page, and the regulator wants “an objective policy, not merely a statement of intent.” For large commercial policies with cover above ₹50 crore, the commission would be printed on the policy itself.
This matters because the paper finds commissions rising far faster than premiums. For life insurance sold through corporate agents such as banks and NBFCs, distributor pay rose 125% between FY23 and FY25 while premium grew 28%. In motor insurance through brokers, commissions rose 259% against premium growth of 34%.
IRDAI: Naming and tracking the offenders
IRDAI proposes to track dark patterns actively and publish what it finds. One of the measures it will use to judge the reforms is the number of insurers and large distributors still using dark patterns.
Through a planned Public Insurance Registry, customers would get “Know Your Insurer” and “Know Your Distributor” tools. Individual salespeople would be tagged to the policies they sell, and records of mis-selling would be made public. Insurers would claw back commission on mis-sold policies.
IRDAI: Other safeguards for buyers
Several related proposals would change the buying experience:
- Direct verification: the insurer must connect directly with the customer before issuing a policy, whatever the channel. The paper suggests OTP checks, Aadhaar face authentication and mobile number verification.
- Direct payment: premiums would go straight from the customer’s own UPI, card or bank account to the insurer, not through an intermediary’s account. Third-party payments would not be accepted.
- Direct claim payouts: claim money would go only to a verified account of the policyholder or nominee, with names matched against both the insurer’s and the bank’s records.
- Written suitability checks: for life policies above a set ticket size, a documented needs analysis would be mandatory. A customer’s signature alone would not protect the seller if the product was unsuitable.
- Named mis-selling practices: the regulator lists 12 examples that would attract action. They include selling a savings plan as a fixed deposit, promising assured returns on ULIP or participating policies, and selling term cover to people with no dependants or not of working age.
IRDAI: What happens next
These are proposals, not final rules. IRDAI has invited comments from policyholders as well as industry. Question 22 of the consultation asks specifically whether the transparency measures are adequate and what should be added. Feedback can be submitted through the web portal at iib.gov.in/dr, either on the form or by uploading an Excel template, or by email to drfeedback@iib.gov.in.
For the ordinary buyer, the direction is clear: prices you can see without handing over your number, claim ratios based on money actually paid, commissions made public, and a record of which sellers mis-sell. How much of that survives consultation will depend partly on whether customers speak up.