Insurance Claim Rejected Despite Corrected Records: Delhi Consumer Commission Backs 76-Year-Old Policyholder
Insurance Claim Rejected despite corrected records led to a dispute before the Delhi Consumer Commission, which ruled in favour of the 76-year-old policyholder.
Insurance Claim Rejected despite corrected records, but the Delhi Consumer Commission backed a 76-year-old policyholder.
NEW DELHI, Insurance Claim Rejected: In December 2023, a 76-year-old woman was rushed into the emergency ward of a Delhi hospital. Somewhere in the paperwork that followed, a doctor wrote down a diagnosis she did not have: chronic kidney disease. Hospital staff corrected the entry before she went home. More than two years later, that one line was still at the centre of a dispute that ended before a consumer commission, which ruled in her favour on September 24.
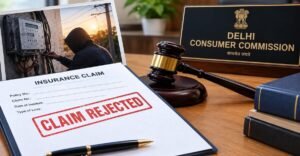
The Delhi District Consumer Commission, comprising president Divya Jyoti Jaipuriar and member Rashmi Bansal, found the insurer guilty of deficiency in service. It ordered the company to reimburse Rs 3.87 lakh, the amount the woman paid out of pocket. It also directed Rs 50,000 as compensation for harassment and Rs 35,000 towards litigation expenses, a total of Rs 4.72 lakh.
Insurance Claim Rejected: Two policies, full disclosure and a clean medical check
In June 2023, the woman bought two “platinum” health insurance policies from the private insurer, with a combined sum insured of Rs 35 lakh. According to the case record, she declared her existing conditions at the time of purchase: diabetes, hypertension and high cholesterol. She then underwent the insurer’s pre-policy medical examination, which showed no history of heart or kidney problems.
Six months later, in December 2023, she was admitted to Max Super Speciality Hospital in Shalimar Bagh. She told the commission that during her emergency admission, the doctor on duty wrongly recorded chronic kidney disease in her file.
She said the hospital corrected this before discharge. An official addendum dated December 30, 2023, amended the record. It was accompanied by normal kidney test results and a letter from her treating doctor confirming she had no earlier history of kidney or heart disease.
Insurance Claim Rejected: Cashless request denied, reimbursement claim rejected
The woman alleged that the insurer refused cashless treatment, so she had to settle the entire hospital bill of Rs 3.87 lakh herself. She then applied for reimbursement.
She stated that the insurer repeatedly asked for further documents and demanded a separate affidavit from the emergency doctor, even though she had submitted the corrected records and clarifications. On April 25, 2024, the company formally rejected the claim, citing non-submission of required documents.
Insurance Claim Rejected: The insurer’s defence
Before the commission, the insurer argued that the policyholder had not provided mandatory medical documents despite repeated reminders. It said an affidavit from the emergency resident doctor was necessary to explain why chronic kidney disease appeared in the initial notes, and that the claim could not move forward without it.
The company also maintained that insurers have a legal right to seek complete medical records, clarifications and past treatment details, including heart and kidney histories, to verify the genuineness and cause of a claim before approving payment.
Insurance Claim Rejected: What the commission held
The commission accepted that the kidney disease entry was a clerical error by the emergency resident doctor. It noted that the correction was made through an official addendum before the patient was discharged. In its view, the discrepancy was not something produced after the claim was filed but was fixed during the hospital stay itself.
On the affidavit demand, the commission found it unnecessary and unreasonable. The hospital had already issued a clarification on its letterhead, the treating doctor had confirmed normal kidney function, and the emergency doctor had amended the record.
The commission acknowledged that insurers are entitled to ask for documents to verify claims. It held, however, that this right cannot be used to repeatedly call on a policyholder for papers already supplied, or for documents that cannot reasonably be obtained in the circumstances.
It also took into account that the woman had disclosed her pre-existing conditions and cleared the insurer’s pre-policy medical examination, which showed no heart or kidney disease.
The commission concluded that the insurer had not processed the claim in a fair, reasonable and diligent manner. It added that the denial of cashless authorisation had a direct financial impact on the complainant. It described the purpose of a cashless facility as allowing an insured person, within policy terms and subject to the claim being admissible, to get hospital treatment without arranging the full cost from personal funds at once.
Insurance Claim Rejected: Where policyholders can turn
The order stated that insurers cannot reject genuine medical claims by repeatedly seeking documents that have already been furnished, particularly when discrepancies were promptly corrected.
Consumers with similar complaints can contact the Delhi consumer helpline at 011-23379146 or the National Consumer Helpline at 1915