Insurer Said No, Court Said Pay: Jaguar Owner Wins Insurance Claim After Rainwater Denial
Jaguar case highlights how insurers assess rainwater-related vehicle damage and the terms of motor insurance policies.
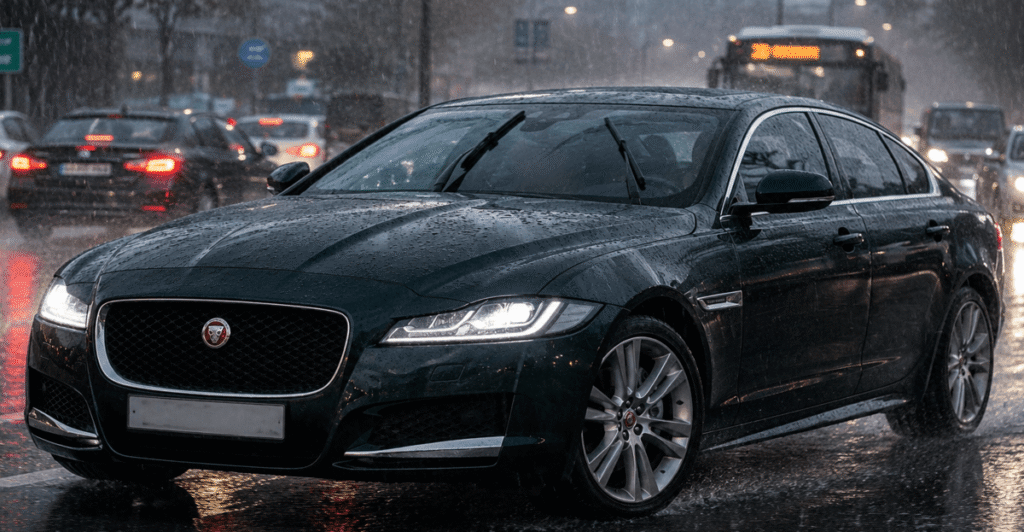
A Jaguar owner has won an insurance claim dispute after the insurer denied coverage for rainwater-related damage.
Jaguar: A District Consumer Disputes Redressal Commission in Chhattisgarh has directed an insurance company to compensate a car owner after it repudiated his claim for rainwater damage to his vehicle, ruling that the insurer could not invoke exclusion clauses it had never furnished to the policyholder.
The bench, comprising commission president Dakeshwar Prasad Sharma along with members Nirupma Pradhan and Anil Kumar Agnihotri, passed the order on August 24, directing the insurer to pay Rs 1.75 lakh toward the claim, Rs 20,000 as compensation for mental agony, and Rs 7,000 toward litigation costs — a total payout of just over Rs 2 lakh.
Also Read: General Insurers’ Underwriting Losses Widen to Rs 45,279 Crore in FY26
Jaguar: What happened: window left open, rainwater entered vehicle
The complainant, the registered owner of a car, had insured his vehicle under a private car policy covering the period from November 29, 2020 to November 28, 2021.
In August 2021, rainwater entered the car after its driver-side window was left partially open, damaging the infotainment system and other components. The insurer deputed a surveyor to assess the loss, who put the repair cost at Rs 1.98 lakh. The complainant, however, maintained that his actual repair expenditure came to Rs 2.73 lakh.
The insurer rejected the claim on February 4, 2022, on two grounds: that damage caused by rainwater ingress was excluded under the policy, and that leaving the window open constituted gross negligence amounting to a breach of policy conditions.
The owner then approached the consumer commission, alleging deficiency in service and unfair trade practice. His case rested on a specific procedural argument — that the insurer had never supplied him with the full terms, conditions, and exclusions of the policy at the time it was issued, and could therefore not invoke those very exclusions to deny his claim later.
Jaguar: Commission finds policy document incomplete, exclusions non-binding
Examining the documents on record, the commission found that the insurance policy issued to the complainant ran to four numbered pages, yet the insurer had placed only three of those pages before the commission. The separate terms-and-conditions document the insurer relied on to justify the rejection ran to six pages and had not accompanied the policy when it was issued to the complainant.
The commission held that because these terms, conditions, and exclusions were not supplied to the complainant along with his policy, they could not be treated as binding on him. It further noted that the six-page terms document produced separately by the insurer could not be read as forming part of the policy itself, given that the policy document the insurer had furnished consisted of only four pages.
On this basis, the commission concluded that the insurer’s repudiation of the claim by relying on exclusion clauses was not justified, and that the rejection amounted to deficiency in service and unfair trade practice.
The commission accordingly directed the insurer to pay Rs 1.75 lakh toward the claim, along with Rs 20,000 for mental agony and Rs 7,000 as litigation costs.
Rainwater-Damaged Infotainment System Triggers Rs 2.02 Lakh Insurer Payout Order