Star Health Insurance: IRDAI Imposes Rs 2 Crore Penalty Over Claims Denial, Deductions
IRDAI has penalised Star Health Insurance Rs 2 crore for violations in Covid claim settlement and claim communication. Here is what the order says.
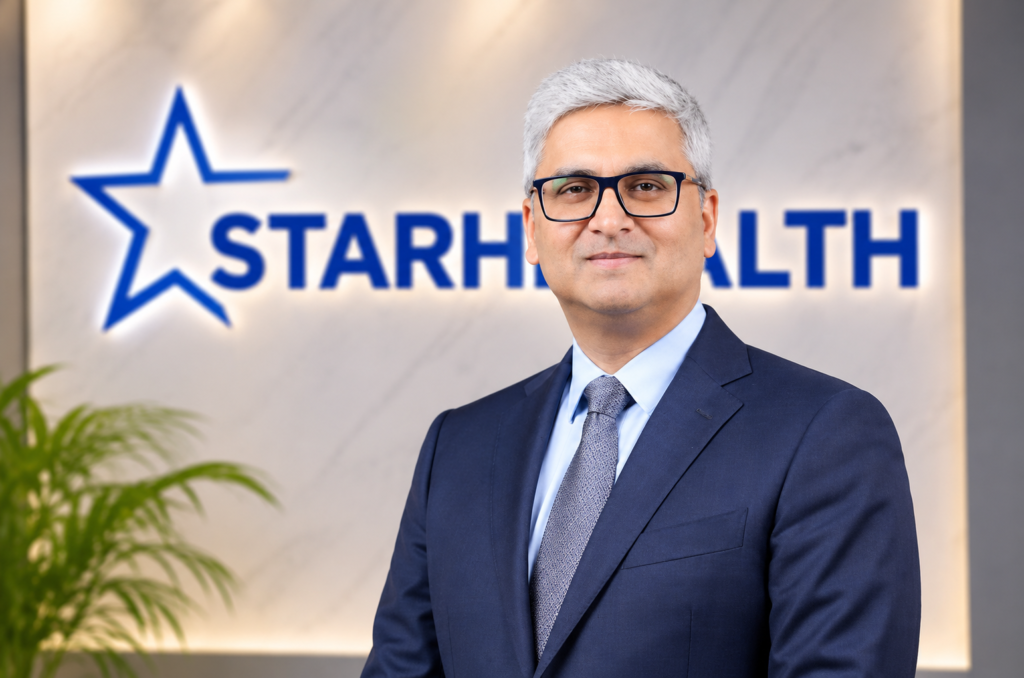
Star Health Insurance CEO Anand Roy
NEW DELHI, Star Health Insurance: The Insurance Regulatory and Development Authority of India (IRDAI) has imposed a total penalty of Rs 2 crore on Star Health and Allied Insurance for violating health insurance regulations in the settlement of Covid-19 claims and in its communication with policyholders. The order, dated 20 November 2026, follows a show cause notice issued on 4 December 2024 after an inspection of the insurer in early 2022.
The regulator levied two penalties of Rs 1 crore each under Section 102 of the Insurance Act, 1938. It also issued cautions, warnings and directions on three other charges and did not press an eighth. The insurer must pay the penalty from its shareholders’ account within 45 days.
Star Health Insurance: Penalty for denying Covid claims on “hospitalisation not required” grounds
The first penalty relates to rules that requires every claim to be settled in accordance with the policy terms and conditions. The inspection found that the insurer had repudiated sampled claims on the ground that the patient did not need hospitalisation and could have been treated at home, citing AIIMS and Union Health Ministry guidelines on home isolation.
Enjoying this story?
Subscribe to our newsletter for fresh stories and expert insights delivered straight to your inbox.
IRDAI noted that the insurer’s Family Health Optima policy covers hospitalisation expenses incurred on the advice of a qualified medical practitioner. It observed that Covid-19 was an exceptional period in which doctors may have acted with extra caution, and that hospitalisation may also have been preferred to isolate patients and protect family members. The insurer ought to have considered this, it said, and held that the claims were processed in a manner inconsistent with the policy terms.
Also Read: Your Investment Account Could Be Hacked This Way: IOSCO Flags Rising Fraud Threat
The Authority also said the insurer did not provide proof that it had told policyholders why hospitalisation was not required, and concluded that no such communication was sent. It advised the insurer to ensure that no arbitrary deductions or denials are made without proper justification.
Star Health Insurance: Second penalty over deductions and claim communication
The second Rs 1 crore penalty covers deductions from claims and the way settlements were communicated. According to the order, many deductions in the sampled cases were attributed to claims being “processed as per GIC rates”, without reference to any policy clause permitting them. The Authority said this was detrimental to policyholders and contrary to a 4 March 2020 circular directing insurers to settle claims in line with policy terms. It noted that in many sampled cases the insurer paid additional amounts after the cases were flagged by the inspection team.
Data submitted by the insurer showed that deductions under “reasonable and customary” charges were highest in FY 2021-22. The Authority said this indicated the clause was being used as a matter of practice rather than in isolated cases. It also said the sample cases the insurer submitted after the hearing differed materially from those identified during the inspection, raising concerns about the reliability of the information furnished.
On communication, the regulator requires insurers to state the reasons for denial or repudiation, refer to the relevant policy conditions, and give details of grievance redressal and the Insurance Ombudsman. The insurer had accepted that a covering letter with grievance and Ombudsman details was not sent during the period because of a technical error. The Authority found that its response was silent on informing policyholders of the specific policy terms behind deductions or repudiations.
Star Health Insurance: Insurer’s submissions
Star Health told the regulator that Covid-19 was an unprecedented situation and that it relied on guidance from bodies such as the WHO, ICMR and AIIMS. It said state health department guidelines issued under the Disaster Management Act and the Clinical Establishments Act were legally binding, and that many hospitals overcharged during the pandemic. The insurer said it applied “reasonable and customary” charges where billing was excessive, in line with policy definitions approved by the Authority. It added that no complaints had been filed before the Ombudsman or any redressal forum in the 15 cases under consideration.
Star Health Insurance: Other charges, compliance and appeal
On Charge 1, the insurer was cautioned for collecting renewal premium on some policies more than 90 days in advance. It attributed the lapse to a technical issue and said it introduced a two-step validation in February 2023.
On Charge 6, the insurer was warned and directed to put in place systems so that hospital discounts are reflected in bills. The final settlement letter must list each allowed, disallowed, non-payable and discount item, along with the sum insured reduced from the policy limit. On Charge 7, the insurer was cautioned and warned after grievance resolution letters were found to omit the name and address of the Insurance Ombudsman. Charge 8, which concerned differences in commission and reward figures reported in regulatory returns, was not pressed after the Authority took the insurer’s reconciliation on record.
The insurer must place the order before its Board and submit the minutes of the deliberations. It must also file an Action Taken Report on the directions within 90 days. It can appeal to the Securities Appellate Tribunal under Section 110 of the Insurance Act, 1938.
Follow us on Twitter for latest updates

Priyam Thakur is a Correspondent at The Insurance Reporter, where he covers insurance regulation and policy in India and globally. Trained as an engineer, he has a knack for dissecting dense numbers...